GCD Australian Regional Meeting
Featured
Australian Regional Meeting 25th July, 2024 from 9.00am - 12.00pm AEST
Australian Regional Meeting 25th July, 2024 from 9.00am - 12.00pm AEST
Register now for our Nordic forum, hosted by SpareBank on 19 September 2024 When: 12:00 - 18:00, 19 September 2024 Where: SpareBank 1 SR-Bank, Stavanger Norway Event website: https://events.globalcreditdata.org/GCDNordicForumStavangerSeptember2024
Climate Risk Focus Group Discussion on Industry/Sectors Wednesday, October 9th at 10:00 EST / 16:00 CET This session will focus on refining the breakdown of industry codes, which play a key role in accurately capturing climate-impacted industries in the GCD Data pools (PD and LGD) Attendees: GCD Member Banks Host: Hale Tatar, GCD
GCD European Conference 2025 Jan 13 – 14, 2025 Frankfurt am Main, Hessen - Germany Conference Event Page
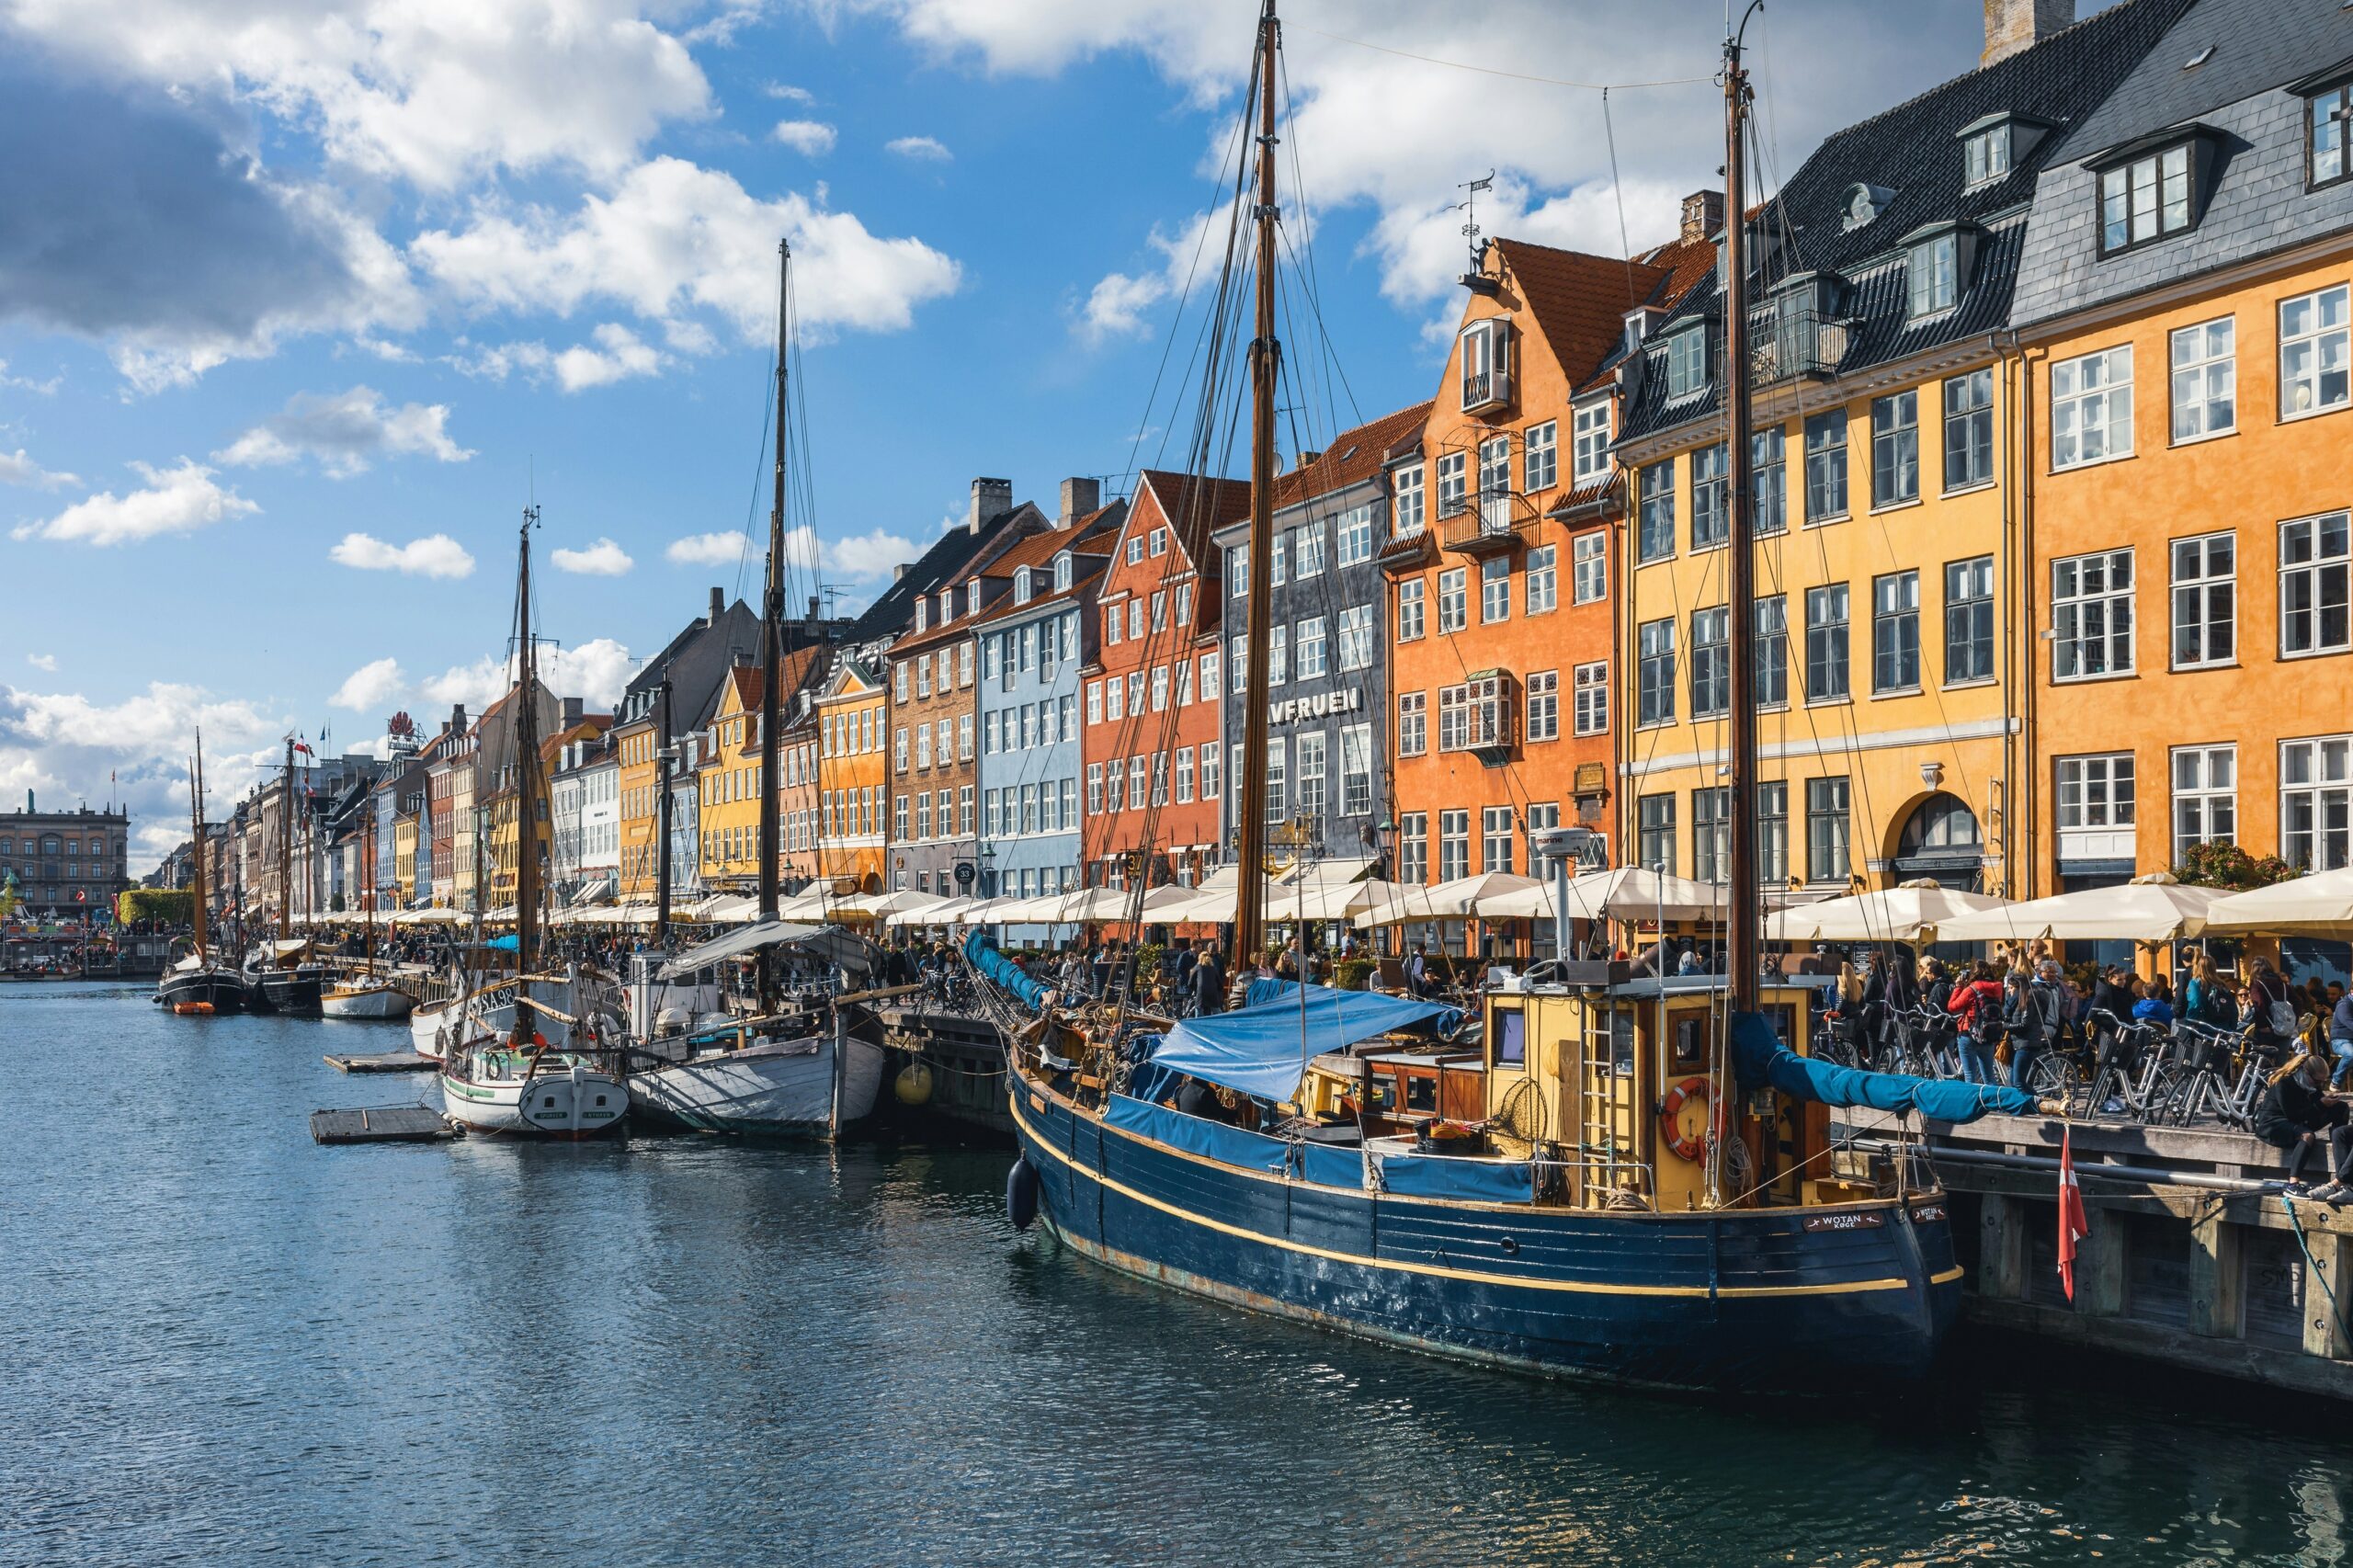
GCD Nordic Conference, 07 May 2025, Copenhagen-Denmark We are pleased to invite you to our one-day GCD conference, with Nordic topics and venue. GCD data is both global and regional, so it makes sense that our conferences need to be at both levels too.

Global Credit Data (GCD) and United Nations Environment Programme Finance Initiative (UNEP FI) have jointly conducted a global survey to evaluate how banks are integrating climate-related risks into their credit risk management frameworks. The survey has been designed to offer a detailed analysis of the methodologies banks currently use to assess climate-related credit risks, with a focus on identifying common practices in modelling approaches and broader risk assessment strategies. Insights from the survey have been incorporated into an upcoming publication, which aims to support the enhancement of climate risk assessment and management methodologies used by banks. The webinar will offer a preview of the forthcoming report and share initial insights from the global survey. It will touch on key themes, including the current scope of climate risk assessments, how results are being used, and trends in the integration of climate risks into credit risk modelling and management frameworks. Register Here

Organised by Global Credit Data (GCD) · Hosted by Capgemini Join senior credit risk leaders from across the financial services industry for a focused, one-day program that turns data into better capital decisions. What to expect: Keynote presentations - understand capital impacts, output-floor readiness, and next-step actions. Peer-driven panels on external loss benchmarking, stress-testing insights, and model-validation best practice. Interactive break-out workshops covering CCAR downturn LGD, climate-adjusted PDs, data-quality/BCBS 239 and low-default portfolio techniques. Case study on LGD representativeness – learn how pooled data can identify sampling bias and refine capital estimates. AI & technology spotlight – live demonstration of accelerators for credit-risk analytics. Insights from GCD’s global PD/LGD database, enabling evidence-based benchmarking across regions and asset classes. High-value networking at hosted breakfast, lunch, and an evening reception in Midtown Manhattan. Space is limited. Register your interest today and we’ll confirm your seat and share the detailed agenda. Register
Session Overview: Overview of the NGFS scenarios and how they can be applied for climate scenario analysis and stress testing. Insights into key methodological choices and use cases based on the recently released NGFS User Guide on the practical application of climate scenarios Speaker: Tina Emambakhsh, European Central Bank (ECB) Registration Link: GCD Webinar NGFS Climate Scenarios

We’re excited to announce our highly anticipated European Conference, taking place in Zurich, Switzerland on March 5–6, 2026. Join senior credit risk professionals from leading European and global banks for two dynamic days of insight, collaboration, and networking.
Webinar on Practical Insights on Transition Planning under the EBA Guidelines on ESG Risk Management This session provides an overview of the EBA Guidelines on ESG Risk Management and discusses their implications for banks and financial institutions. In particular, it focuses on the role of transition planning as a forward-looking tool for managing climate-related risks within existing risk management frameworks. The presentation introduces a practical step-by-step approach to developing an ESG transition plan for bank portfolios. It will cover key methodological elements, including the definition of suitable key risk indicators (KRIs), the use of reference pathways and climate scenarios such as CRREM, IEA, and NGFS to assess portfolio alignment, and approaches for translating transition planning into financial risk metrics. The session aims to provide practical insights into how banks can operationalize transition planning and integrate it into their broader risk management processes. Speaker: Thomas Wulf, Head of ESG and Novel Risk, d-fine Register here
Webinar: A strategy for modelling Environmental Risks that matter Integrating environmental risks into modelling frameworks is a key issue facing banks today. The multitude of risks, and their forward-looking nature make inclusion a difficult problem, where traditional approaches fall short. In this talk, we present the novel solution applied at ABN AMRO. The most material risks are first identified based on estimated costs to clients and academic literature, and are then modelled via existing risk driver modifications. Speakers: Mats Draijer coordinates the bank-wide modelling efforts on Environmental Risk at ABN AMRO. Besides this, he works on various IFRS9 & Stress Testing models and has previous experience in Liquidity & Interest Rate Risk Modelling. Mats' background is in Applied Mathematics and Financial Engineering, and he has completed the CFA Program. Marc Brouwers is a Risk Modeller in ABN AMRO’s Economic Capital team, where he develops statistical algorithms and has played a key role in pioneering a bank-wide approach to integrating environmental risks. Marc holds degrees in Physics and Economics, and earned his PhD from the University of Cambridge Register here
GCD Toronto Risk Conference · 29 September 2026 Join senior credit risk leaders from across the financial services industry for a focused, one-day program that turns data into better capital decisions. What to expect: Keynote presentations - understand capital impacts, output-floor readiness, and next-step actions. Peer-driven panels on external loss benchmarking, stress-testing insights, and model-validation best practice. Case study on LGD representativeness – learn how pooled data can identify sampling bias and refine capital estimates. AI & technology spotlight – demonstration of accelerators for credit-risk analytics. Insights from GCD’s global PD/LGD database, enabling evidence-based benchmarking across regions and asset classes. Climate & ESG integration Climate risk use cases from Canadian banks and Integration into credit risk models. High-value networking at hosted breakfast and lunch